What can be packaged?
A business owners policy (BOP) generally combines general liability, business property and business income. A commercial package policy (CPP) offers more flexibility. Eligibility and included coverage vary by carrier.
Insurance options for rental properties and Long Island businesses. Get personal guidance on the coverage that fits your needs.
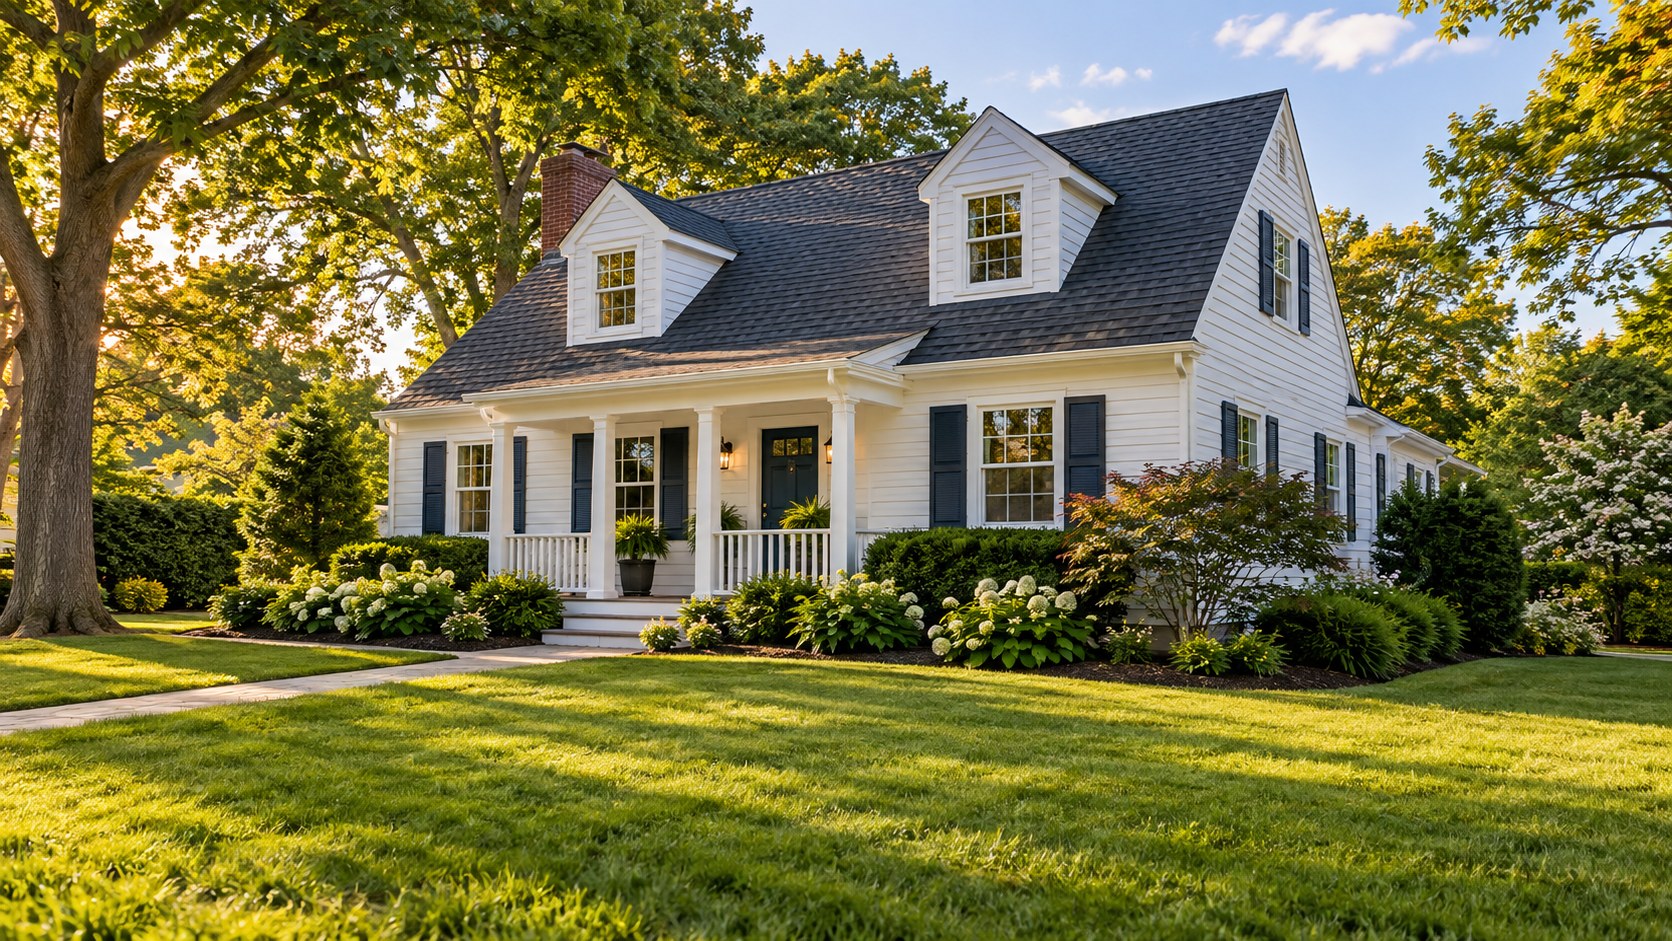
A rental property has different insurance needs than the home you live in. We’ll review occupancy, property details and liability exposures to help you explore your options.
Request a landlord quoteHave a current policy? Your declarations page is a helpful starting point.
Explore protection for the dwelling and other insured property against covered losses.
Review liability protection for covered injuries or property damage associated with your rental.
Consider coverage for lost rental income after covered property damage, subject to policy terms.
Discuss umbrella, flood and other options based on your property’s exposures and carrier availability.
Your work, your people and your premises shape your insurance needs. Start with your business type.
From jobsite liability to the tools in your truck, a contractor’s exposures extend beyond the office.
Subcontractor conditions, height restrictions, completed operations and employee-injury exclusions deserve a close review.
Equipment, employees, guests and deliveries all bring different risks. Alcohol service adds another exposure to review.
If you lease, check responsibility for the kitchen buildout, glass and landlord insurance requirements.
Consider your inventory, customers and staff alongside the risks that come with online sales or deliveries.
Tenant improvements, seasonal inventory and off-site events may need specific attention.
A building’s construction, tenants and occupancy matter. Share the tenant mix and property details so we can review the right exposures.
A restaurant or other specialized tenant can change the information carriers need.
A business owners policy (BOP) generally combines general liability, business property and business income. A commercial package policy (CPP) offers more flexibility. Eligibility and included coverage vary by carrier.
Workers’ compensation, NY disability / Paid Family Leave, commercial auto, umbrella, bonds and specialty coverages may be placed separately. A package is a starting point for reviewing your needs.
Start with a quote request. Tell us how the property is occupied or what your business does.
Share declarations pages if available. We may follow up for loss history, property values or other underwriting information.
Review available options, limits and exclusions with an agent before choosing coverage.
A policy designed for an owner-occupied home may not fit a rental. Tell your agent about tenant occupancy, vacancies, short-term rentals or any change in use so the appropriate policy can be reviewed.
The landlord generally insures the building. You may still need coverage for inventory, equipment, furnishings and tenant improvements. Your lease may set additional requirements.
No. A request starts the review process. Coverage must be confirmed and bound through the appropriate carrier or authorized representative.
Choose the request that fits. Share what you know—we can follow up for any additional information needed.
For tenant-occupied homes and rental properties. Start with the property address, occupancy and basic details.
Start a landlord requestFor contractors, restaurants, retailers and commercial property owners. Tell us about your operations.
Start a business requestForms open in a new tab. Requesting a quote does not bind coverage.
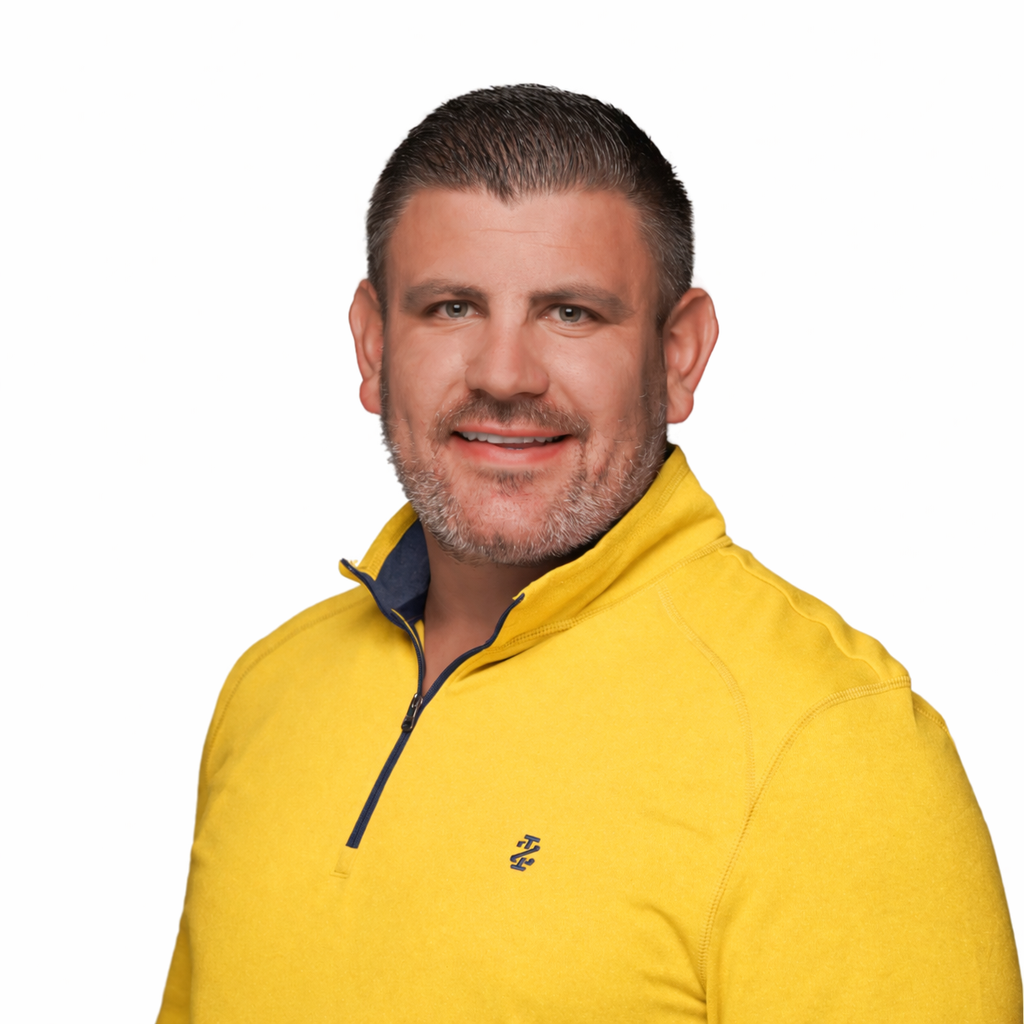
I’m Jared Garcia, owner of BLI Insurance Agency and a Long Island business owner with more than 20 years of experience in real estate. As co-owner of Weichert, Realtors® – Performance Homes in Farmingdale, I understand the responsibilities that come with owning property, managing investments and running a business.
At BLI Insurance Agency, I work with landlords and business owners to understand their exposures and explore coverage that fits their needs. You can expect straightforward conversations, clear explanations and personal attention from someone who understands the local market.